
Critical Shifts:
-
Multi-Year High for Auto Credit Access: Credit availability reached its highest level since November 2015, driven by a 73.9% approval rate—the fifth consecutive monthly increase.
-
Looser Terms Driving Growth: Improvements were primarily fueled by longer loan terms (a record 31.3% exceeding 72 months) and an increase in subprime borrower share to 16.6%.
-
Captives and CPO Leading Spikes: Captive lenders saw the strongest year-over-year credit expansion at 14.9%, while Certified Pre-Owned (CPO) vehicles recorded the largest month-over-month channel gain at 1.2%.
______________________________________________________
Auto credit availability improved for the fourth consecutive month in August, reaching its highest level since November 2015, according to the Dealertrack Credit Availability Index.
The All-Loans Index rose 0.4% from July to 105.3 and was up 7.7% year over year.
The improvement was driven largely by looser loan structures, including longer terms and a higher share of loans involving negative equity. The subprime share also increased, while a modest widening in the yield spread partially offset those gains.
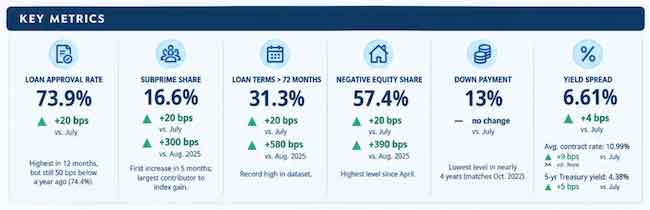
The overall loan approval rate rose 20 basis points in August to 73.9%, its fifth consecutive monthly increase and highest level in 12 months. However, the rate remained below the 74.4% recorded a year earlier, and the pace of monthly improvement continued to slow.
The share of loans to subprime borrowers increased to 16.6%, up 20 basis points from July and 300 basis points from a year ago. It was the first monthly increase in five months and the largest contributor to August's index gain.
Longer loan terms also reached a record. The share of loans exceeding 72 months increased 20 basis points to 31.3%, up from 25.5% a year ago.
Negative equity increased 60 basis points to 57.4%, the highest level since April. The share was up 390 basis points from a year ago and represented the second-largest contributor to the monthly index gain.
Down payments remained at 13%, unchanged from July and matching October 2022 for the lowest level in nearly four years. The August figure was down from 13.6% a year earlier.
The average contract rate increased 9 basis points to 10.99%, while the five-year Treasury yield rose 5 basis points to 4.38%. As a result, the yield spread widened 4 basis points to 6.61%.
Independent Used Credit Access Improves
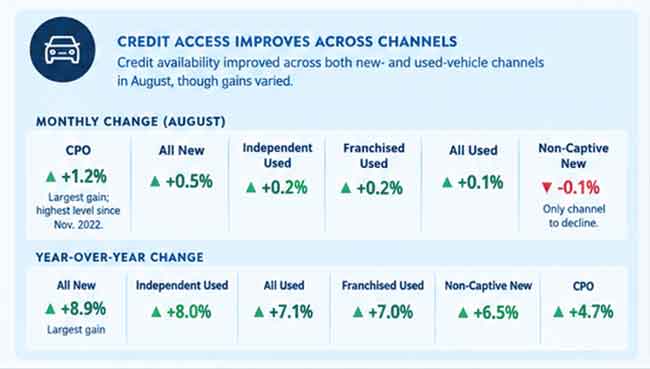
Credit availability improved across both new- and used-vehicle channels in August, although gains varied.
Certified pre-owned posted the largest monthly increase, rising 1.2% to its highest level since November 2022. All New increased 0.5%, while Independent Used and Franchised Used each rose 0.2%. All Used increased 0.1%, with each of those three channels reaching a series high.
Non-Captive New declined 0.1%, making it the only channel to post a monthly decline.
Year over year, All New recorded the largest gain at 8.9%, followed by Independent Used at 8%. All Used rose 7.1%, Franchised Used increased 7%, and Non-Captive New was up 6.5%. CPO posted a 4.7% gain.
Among lender types, Captives posted the largest monthly increase at 1%, followed by Banks at 0.8% and Finance Companies at 0.5%. Credit Unions declined 0.1%.
Captives also led the year-over-year gains, up 14.9%, followed by Banks at 13.4%. Credit Unions increased 8.1%, while Finance Companies rose 8%.